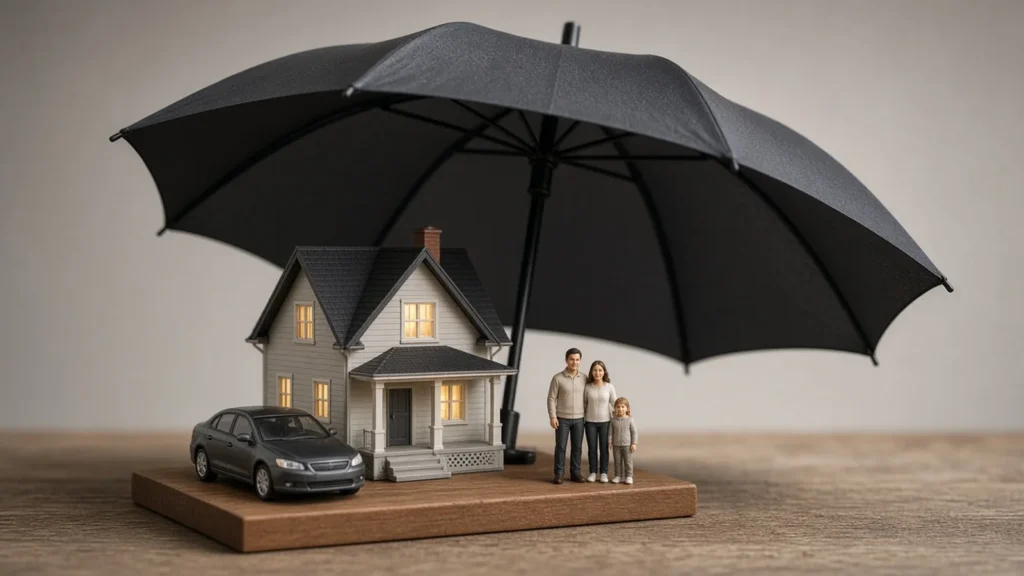
Most people carry liability coverage through their auto and homeowners or renters insurance, and assume that is enough. But serious accidents can lead to claims that exceed those limits. When that happens, the person found responsible may have to pay the difference from savings, investments, or future income. Umbrella insurance is designed to add an extra layer of liability protection above your existing policies, often at a relatively modest cost for the amount of coverage it provides.
This guide explains how umbrella insurance works, who tends to benefit from it, what it covers and excludes, and how to decide how much you need.
What Is Umbrella Insurance?
A personal umbrella policy is excess liability insurance. It kicks in after the liability limits of your underlying policies, usually auto, homeowners, renters, and sometimes watercraft, have been used up. Umbrella policies are commonly sold in increments, often starting at one million dollars of coverage.
A simple example
Imagine you cause a car accident that seriously injures another driver, and a court awards damages above your auto liability limit. Your auto insurer pays up to its limit. Your umbrella policy can then pay the remaining amount, up to the umbrella’s limit, instead of the difference coming from your personal assets.
What Umbrella Insurance Typically Covers
- Bodily injury liability: Injuries to others for which you are legally responsible, such as a serious car accident or a guest’s fall at your home.
- Property damage liability: Damage you cause to someone else’s property.
- Personal injury claims: Many umbrella policies cover certain claims that standard policies may not, such as libel, slander, defamation, false arrest, or invasion of privacy. Coverage varies by insurer.
- Legal defense costs: Umbrella policies often pay defense costs, sometimes in addition to the policy limit.
- Worldwide coverage: Many policies cover incidents that happen outside your home country, subject to terms.
In some situations, an umbrella can also provide coverage for claims that your underlying policy does not cover at all, after a self-insured retention, which works much like a deductible.
What It Usually Doesn’t Cover
- Damage to your own property or injuries to yourself.
- Intentional or criminal acts.
- Business activities and professional liability, which require commercial coverage. See our guide to business insurance basics.
- Contractual liability you agreed to take on.
- Certain vehicles, aircraft, or watercraft, depending on the policy.
Who Should Consider an Umbrella Policy?
Umbrella insurance is not only for the wealthy. Lawsuits can target future earnings as well as current assets. You may want to consider it if any of these apply:
You have significant assets or income
Home equity, savings, investments, and a solid income can make you a more attractive target for larger claims.
You have higher-risk exposures
- A swimming pool, trampoline, or hot tub.
- A dog, especially one that interacts with visitors.
- Teen drivers in the household.
- Rental property you own.
- Frequent entertaining or hosting events.
- Boats, motorcycles, or recreational vehicles.
- Coaching youth sports or volunteering on a nonprofit board.
You have an active public presence
If you post opinions online, write reviews, or speak publicly, coverage for defamation-type claims may be valuable.
How Underlying Coverage Requirements Work
Insurers typically require you to carry certain minimum liability limits on your auto and home policies before they will sell you an umbrella. This makes sense: the umbrella is designed to sit on top of solid base coverage, not replace it. You may need to raise your underlying limits, which can add to the total cost. Many insurers also offer discounts if your umbrella, auto, and home policies are with the same company. For more on base coverage, read our guides to homeowners coverage types and car insurance premiums.
How Much Umbrella Coverage Do You Need?
There is no single rule, but a common approach is:
- Add up your net worth: Home equity, savings, investments, and other assets.
- Consider your future income: Judgments can sometimes reach future wages.
- Assess your risk exposures: Pools, teen drivers, rental properties, and so on.
- Compare with your existing liability limits: The umbrella should cover a realistic gap between your underlying limits and what you could lose.
Many people start with the lowest available increment and increase coverage as their assets and exposures grow. A licensed agent or independent adviser can help you evaluate your situation.
What Affects the Cost?
Umbrella premiums depend on the amount of coverage, the number of homes, vehicles, and drivers in your household, driving records, risk factors like pools or watercraft, and where you live. Because the umbrella only pays after underlying coverage is exhausted, its cost per dollar of coverage is often lower than the underlying policies. Shopping with several insurers and bundling can help.
Tips for Buying an Umbrella Policy
- Make sure the umbrella “follows form” or clearly lists how it relates to your underlying policies.
- Ask whether defense costs are paid in addition to the limit or reduce it.
- Check coverage for all household members, including students living away from home.
- Disclose all vehicles, properties, and watercraft to avoid gaps.
- Review the policy when you buy property, add drivers, or take on new risks.
Real-World Situations Where an Umbrella Helps
A serious multi-car accident
A moment of distraction leads to a collision involving several vehicles and multiple injured people. Medical bills, lost wages, and pain-and-suffering claims from several people can quickly add up beyond a typical auto liability limit. The umbrella can respond once the auto policy has paid its maximum.
An injury at a backyard gathering
A guest is badly hurt diving into a shallow part of your pool. Long-term medical care and lost earning capacity can lead to a large claim. Your homeowners liability coverage pays first, then the umbrella can help with the rest.
A teen driver’s mistake
Newly licensed drivers have less experience and, statistically, higher accident risk as a group. If a teen in your household causes a serious accident while driving a family car, the parents may face significant liability. Many families add umbrella coverage when a teen starts driving for this reason.
An online post that leads to a lawsuit
A negative review or social media post leads to a defamation claim. Standard homeowners policies may not cover this type of claim, while many umbrella policies include personal injury coverage that can help pay for a legal defense, subject to the policy terms.
Umbrella Insurance vs. Simply Raising Your Limits
You might wonder why you would not just raise the liability limits on your auto and home policies instead. The answer is that underlying policies have maximum limits, and the cost of each additional increment can rise. An umbrella provides a single large pool of coverage that sits above all your eligible policies at once, so the same coverage protects you whether the claim arises from your car, your home, or your boat. For many households, raising underlying limits to the level the umbrella insurer requires and then adding the umbrella is the most efficient combination.
Frequently Asked Questions
Does umbrella insurance cover my business?
Generally no. Personal umbrella policies exclude business activities. Business owners usually need a commercial umbrella or excess liability policy.
Can renters buy umbrella insurance?
Yes. Renters can usually buy an umbrella as long as they carry the required underlying liability limits on a renters policy and auto policy. See our guide to renters insurance.
Does umbrella insurance cover rental properties I own?
It can, if the properties are disclosed and covered by appropriate underlying landlord policies with required limits.
Is umbrella coverage worth it if I don’t have many assets?
It depends on your income, risks, and peace of mind. Even without large assets, future earnings can be at stake, so it is worth getting a quote and weighing the cost.
Conclusion
Umbrella insurance adds a broad layer of liability protection above your auto and home policies, often for a modest premium relative to the coverage. It is especially worth considering if you have meaningful assets or income, teen drivers, pools, pets, rental properties, or a public profile. Start by reviewing your underlying limits, estimate what you could lose in a serious lawsuit, compare quotes, and read the exclusions carefully so the policy truly fits your life.